

Some folks have been asking for clarification on disaster loss claims, specifically with regard to the value of a damaged or destroyed home.
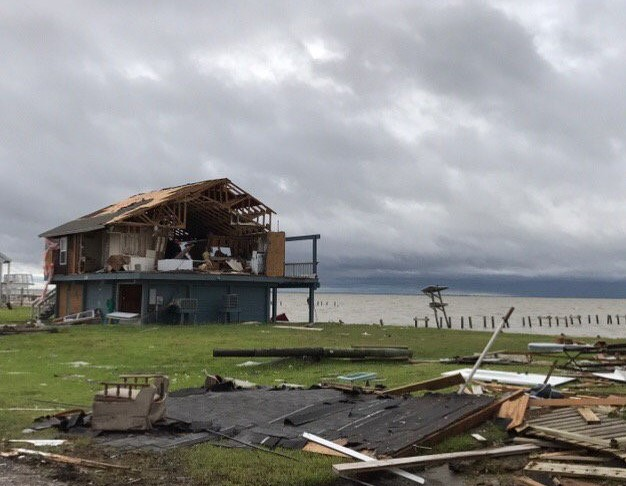
A Rockport, Texas, home severely damaged by Hurricane Harvey, which made its first landfall on Aug. 25 at the Gulf Coast town.
(Photo courtesy National Weather Service, Corpus Christi, via Twitter)
…
At issue is how a home’s fair market value factors into a disaster tax claim.
I’m sorry to report that a property’s high value — I’m talking for sale purposes, not just your personal appreciation and assessment of the house — won’t help you get more tax relief.
Here’s why.
Begin with basis: The financial factor key in determining your disaster loss claim is basis. Let me go to the ol’ blog’s glossary, which says:
Basis — Sometimes is referred to as cost basis, is a consideration when you sell an asset and must determine if you owe any taxes on any profit. Basis can be adjusted, taking into account, for example, improvements and depreciation when the asset is real estate or transaction fees and previously paid taxes in the case of stocks or mutual funds. Correct basis will enable you to accurately compute how much profit you make, which could determine how much, if any, taxes you might owe.
A real property’s basis starts with what you paid for it. This includes any down payment, which represents equity, as well as any mortgage you took out to buy the house.
Let’s say you buy a house for $250,000, having put down $50,000 and taking out a loan for the rest. The property’s cost basis is the full $250,000.
But that’s just the starting point.
Certain fees and other expenses you pay when you buy a home — check your closing statement! — also are added to your basis in the property.
And if you add a room or do extensive landscaping, that could increase your home’s basis.
Let’s say your improvements etc. added $25,000 to your home’s basis, making it $275,000.
That’s the figure you’d use if you were selling to determine your profit that’s potentially subject to capital gains. For example, your neighborhood is hot and you could sell your home for $400,000. That selling price minus your basis of $275,000 gives you a profit of $125,000.
Since that’s under the $250,000 tax exclusion ($500,000 for married jointly filing home sellers) for home sale profit, you don’t owe any tax.
But you’re not selling: Now this selling scenario is where the tax code gets confusing when it comes to claiming disaster losses.
Some folks think that since they could have sold their home for big bucks, that’s that value they should use when seeking tax relief from the Internal Revenue Service for their loss. After all, they argue, they want to rebuild or repair their home so that they’re back to their pre-disaster property state.
Sorry.
As the Form 4684 example below shows, although the IRS wants to know your home’s pre- and post-disaster values, the property’s 400 grand marketable value generally doesn’t really affect your claim.
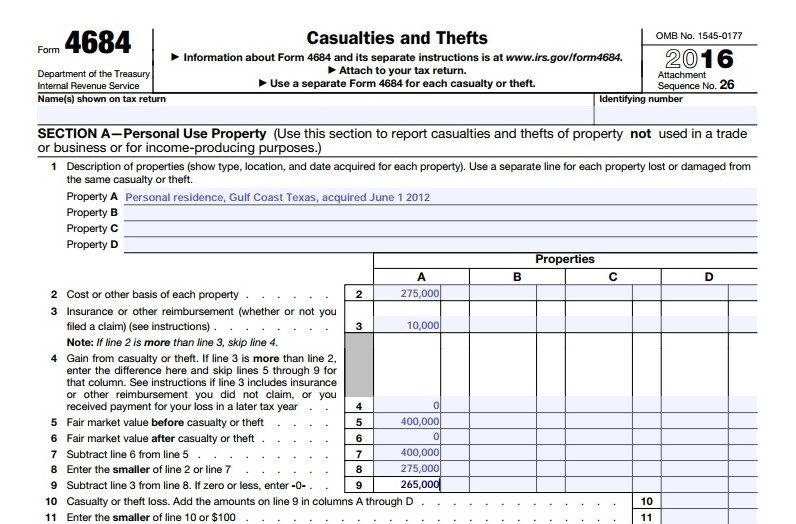
Even though in this example the home was a total loss (line 6), the tax code only lets you claim the decrease in the property’s fair market value after the disaster or its basis. In most cases, that allowable amount is the owner’s basis. You can’t claim, in this case, the $400,000 you could have sold it for before the catastrophe.
Less than total loss issues: And if your house took a hit, but wasn’t a total loss — say your roof was ripped off and the two-car garage collapsed, but the main structure is OK — that relatively good news could turn into bad tax relief news.
In the example below shows, the post-disaster value actually reduces the owner’s loss claim.
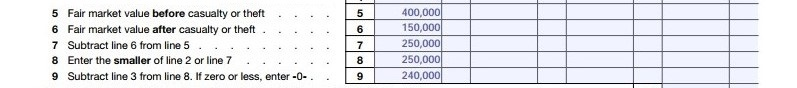
Basically, while the tax code will help you get some tax relief when you suffer a major loss, the IRS wants to make sure you don’t use it to inflate the damage.
Deduction, not a reimbursement: And remember, this is an itemized claim on Schedule A (line 20). That means it’s a deduction, which, unlike a credit, isn’t a dollar-for-dollar tax break. You are not going to get tax money back from Uncle Sam for the total you come up with on Form 4684.
Rather, your loss claim will add to your overall itemized deductions. Those will then reduce your adjusted gross income to a smaller taxable income level.
Yes, it is frustrating. You’re hoping to rebuild at your pre-disaster property level, but you’re not getting enough from the IRS or your insurance to fully cover that.
The only consolation I can offer is that the disaster tax loss claim could at least get you something.
You also might find these items of interest:
- Form 4684, a disaster victim’s best friend
- How to help Hurricane Harvey recovery efforts
- IRS grants tax relief to Texans hard hit by Hurricane Harvey
